How Personal Injury Settlements Are Distributed: A Step-by-Step Guide for Law Firms
A step-by-step guide to the settlement disbursement process, from the trust deposit and lien payoffs to the settlement statement and final payout, with a worked example.
On this page
When a personal injury case settles, the money does not go straight to the client. The settlement check is deposited into the firm's client trust account. Once the funds clear, the firm pays its attorney fee, reimburses case costs, pays medical liens and other claims, and sends the rest to the client. The client approves every number on a signed settlement statement before anyone gets paid.
That is the short version. Below is the full settlement disbursement process, with a worked example, so your team can handle each payout the same way every time.
Who gets paid from a personal injury settlement?
Most settlements are split between four groups:
- The law firm, for its contingency fee
- The firm, again, for case costs it advanced, such as filing fees, medical records, and expert fees
- Lienholders, such as hospitals, doctors, health insurers, Medicare, and Medicaid
- The client, who receives the net amount
Some cases also include a referral fee to another attorney. Every one of these payments comes out of the trust account, and every one must appear on the settlement statement.
The settlement disbursement process, step by step
Step 1: Get the release signed and the check issued
The client signs the release, and the firm sends it to the insurance company. The insurer then issues the settlement check or wire. Track the date you sent the release so you can follow up if payment is late.
Step 2: Deposit the funds into the client trust account
Settlement money belongs to the client until it is distributed, so it goes into your IOLTA or client trust account, never your operating account. Record the deposit on that client's ledger the same day.
Then wait for the funds to clear. Paying out against a check that has not cleared can mean using other clients' money, which is one of the most common trust account violations.
Step 3: Confirm final lien amounts
Do not pay liens based on estimates. Request a written payoff letter from every lienholder. For Medicare, you need the final demand letter before you pay.
This step causes most delays, so start lien work when the case settles, not when the check arrives. If you negotiated reductions, get the reduced amount in writing.
Step 4: Calculate the attorney fee and case costs
Pull up the signed contingency fee agreement. It should say whether the fee is calculated before or after case costs are deducted. That detail changes what the client receives, so follow the agreement exactly.
Total the case costs from your records and attach receipts or an itemized list.
Step 5: Prepare the settlement statement
The settlement statement, also called a closing or disbursement statement, shows:
- Gross settlement amount
- Attorney fee and how it was calculated
- Itemized case costs
- Each lien, by name, with the original and negotiated amount
- Any referral fee or other deduction
- Net amount to the client
Under ABA Model Rule 1.5(c), the client must receive a written statement showing the outcome and how the payout was calculated. Most states follow a version of this rule, but check your own state's requirements.
Step 6: Review the statement with the client and get a signature
Send the statement before you meet so the client has time to read it. Walk through each line, especially the liens. A client should never learn about a lien for the first time on the settlement statement.
Get the client's signature approving the distribution before any money moves.
Step 7: Disburse the funds from trust
Pay the fee to your operating account, reimburse costs, pay each lienholder, and pay the client. Make sure every payment matches the signed statement and that the client's ledger ends at zero, never below.
If part of the money is disputed, for example a lien still in negotiation, hold only that amount in trust and pay out the rest. ABA Model Rule 1.15(e) covers this situation.
Step 8: Reconcile, record, and close the file
Record each payment on the client ledger. Your next three-way reconciliation should show the bank statement, the trust account journal, and the client ledgers all in agreement. Save the signed statement, payoff letters, and proof of payment. The ABA model rule calls for keeping trust records for five years after the representation ends, and some states require longer.
A worked example
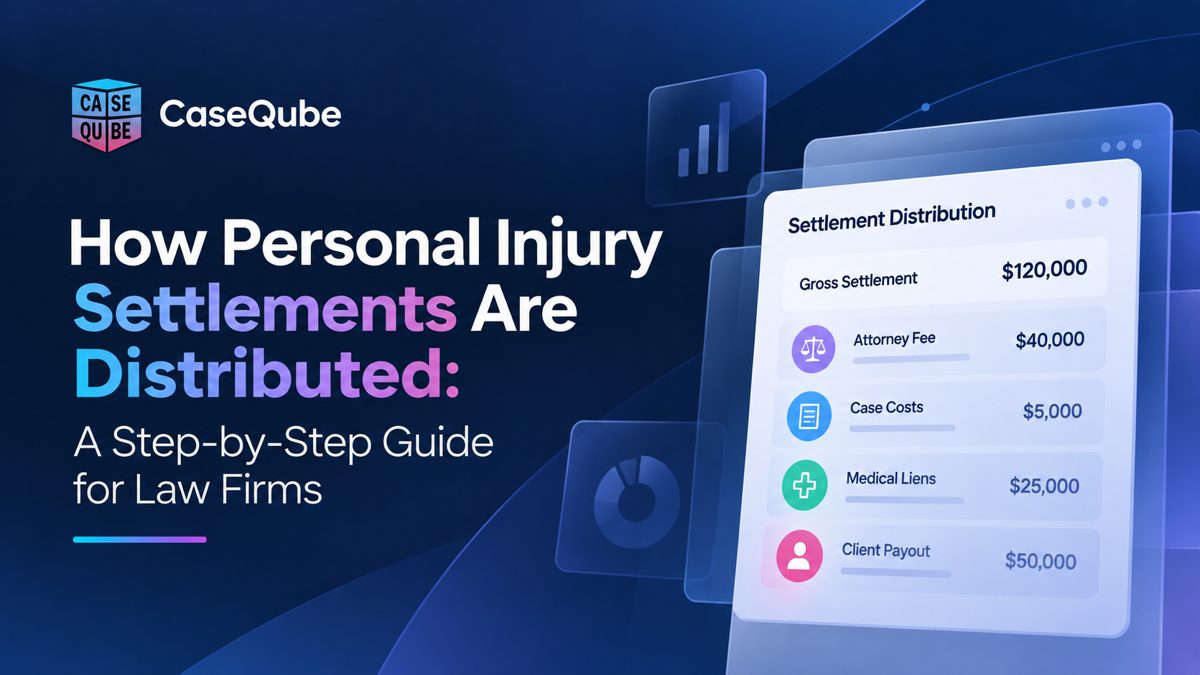
Here is a sample case with a $120,000 settlement, a one-third fee calculated before costs, and $5,000 in case costs. The medical liens were $32,000 and were negotiated down to $25,000.
| Line item | Amount |
|---|---|
| Gross settlement | $120,000 |
| Attorney fee (33⅓% of gross) | $40,000 |
| Case costs | $5,000 |
| Medical liens (reduced from $32,000) | $25,000 |
| Net to client | $50,000 |
If the same agreement calculated the fee after costs, the fee would be one-third of $115,000, or $38,333.33. The client would receive $51,666.67. The difference comes entirely from the wording of the fee agreement.
Common mistakes to avoid
- Paying out before the settlement check clears
- Using estimated lien amounts instead of payoff letters
- Missing a lien, especially Medicare or a health plan
- Moving the fee to operating before the client signs
- Leaving a client ledger with a negative balance
- Vague cost entries like "miscellaneous expenses"
How to speed up settlement distribution
Most delays come from three places: lien resolution, chasing documents, and building the statement by hand. Start requesting payoff letters as soon as the case settles. Keep case costs updated throughout the case, not at the end. Use one template for every settlement statement.
Software helps here too. CaseQube's personal injury settlement workflows calculate payout allocations and attorney splits from the case data, and its legal accounting tools keep trust balances in the same system as the matter.
Frequently asked questions
How are personal injury settlements distributed?
The settlement is deposited into the firm's client trust account. After the funds clear, the firm deducts its contingency fee and case costs, pays medical liens and other claims, and pays the remaining balance to the client, as shown on a signed settlement statement.
Who gets paid first in a personal injury settlement?
All payments are made from trust after the funds clear and the client signs the settlement statement. Liens with legal priority, such as Medicare, Medicaid, and some health plans, must be resolved before the client receives their share.
How long does a law firm have to distribute settlement funds?
There is no single national deadline. ABA Model Rule 1.15 requires lawyers to deliver funds promptly, and some states set specific timeframes. Most delays come from lien resolution.
Can a law firm disburse settlement funds before the check clears?
No. Paying out before funds clear can mean drawing on other clients' money in the trust account, which can lead to bar discipline.
What goes on a personal injury settlement statement?
The gross settlement, the attorney fee and how it was calculated, itemized case costs, each lien with its amount, any other deductions, and the client's net recovery.
Is the attorney fee calculated before or after case costs?
It depends on the contingency fee agreement. Calculating the fee after costs gives the client more money, so the agreement must state the method in writing.
Does the client have to sign the settlement statement?
Firms should get the client's signed approval before disbursing. It confirms the client agreed to every deduction and protects the firm if questions come up later.
Can a law firm hold back part of a client's settlement?
Yes, but only the disputed portion, such as an unresolved lien. The undisputed amount should be paid to the client promptly.
What happens if medical liens are more than the settlement?
The firm usually negotiates reductions with lienholders. Government liens like Medicare have their own reduction rules, and private providers often accept a discount.
How long should a firm keep settlement disbursement records?
The ABA model rule calls for five years after the representation ends. Some states require longer, so check your state bar's rules.
Ready to simplify your case management?
See how CaseQube keeps every matter, document, and deadline in one place.
Book a DemoRelated posts
Case Management vs. Matter Management: What's the Difference for Law Firms?
Every case is a matter, but not every matter is a case. A plain guide to what each term means for a law firm, how they compare, and which one your firm needs.
 Ramit KaurOctober 13, 2026 · 8 min read
How to Run a Conflict Check at Your Law Firm (With a Checklist)
A step-by-step guide to running a conflict check at your law firm, from collecting names at intake to documenting the decision, plus a checklist your team can use on every new matter.
Ramit KaurOctober 13, 2026 · 9 min read
Client Intake Best Practices for Mid-Size Law Firms in 2026
Mid-size firms rarely lose leads from lack of effort. They lose them to too many front doors and no single owner. Here is what to measure and what to change.
Ramit KaurOctober 13, 2026 · 7 min read